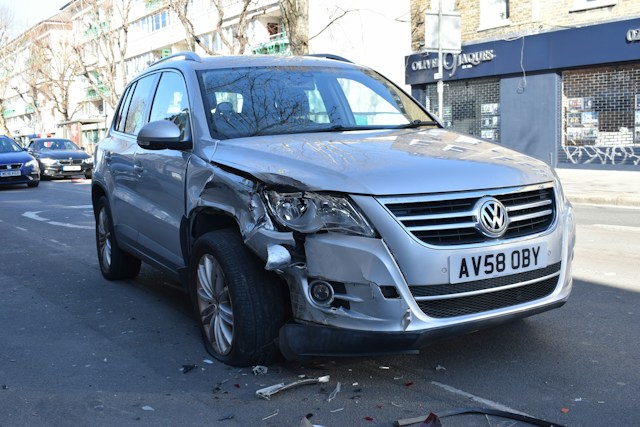
Hempstead is among the most populated towns in Nassau County, with a road network that handles heavy commuter and commercial traffic on a daily basis. Routes like Fulton Avenue, Peninsula Boulevard, and Front Street see thousands of vehicles pass through, and the volume alone creates conditions where collisions are frequent and fault is rarely straightforward. When a crash does happen here, the path forward for an injured person often runs directly through an insurance company looking to pay as little as possible. Hempstead car crash lawyers can help clients navigate that process by building cases that withstand scrutiny when an adjuster starts picking a claim apart.
Every record, medical visit, and piece of evidence has to tell the same story, and it has to do so before an insurer finds a reason to challenge it. For anyone in Hempstead dealing with the aftermath of a collision, understanding how legal teams approach that task is the first step toward protecting a claim from being undervalued or dismissed.
Start With a Fixed Timeline
Investigators build an account showing where each vehicle traveled before impact. They compare crash reports, photographs, traffic signals, vehicle damage, and available surveillance footage. A consistent timeline helps separate confirmed facts from assumptions and exposes gaps that an insurer can exploit.
Scene evidence includes photographs of vehicle positions, road conditions, skid marks, debris, and visible injuries. Witness interviews should record what each person saw without speculating about speed or intent. Investigators also preserve dispatch records and requests for nearby video before routine retention periods erase files.
Build Medical Proof
Medical records must connect the collision to the injuries claimed. A case file usually tracks emergency care, diagnostic testing, follow-up visits, treatment recommendations, work restrictions, and changes in daily activities. The timeline should explain when symptoms began and how providers linked them to the crash.
Gaps in treatment give insurers an argument that an injury improved or came from another cause. A case team therefore collects appointment records, explanations for missed visits, medication information, and prior medical history when relevant. Consistent reporting helps doctors and legal counsel address questions without overstating the injury.
Prove Liability With Records
Fault evidence must show what each driver did before the collision. Investigators examine traffic rules, right-of-way issues, lane positions, turn signals, phone records when available through lawful process, and statements made after impact. The claim should distinguish direct evidence from conclusions drawn later.
A police report can support the account, but it does not replace independent evidence. Photographs, witness statements, vehicle damage, and scene measurements can correct an incomplete report. The case file should preserve original images and identify who collected each record, when it was obtained, and what it shows.
Calculate Every Loss
A demand should connect each dollar to a document or a clear calculation. Medical bills support past treatment expenses, while wage records and employer statements support missed work. Future losses require medical opinions, work restrictions, or other evidence that explains why additional care or reduced earnings follows from the crash.
Non-economic harm also requires a factual record. A claimant can document pain, sleep disruption, household limitations, and changes in regular activities through treatment notes and contemporaneous personal records. Specific examples carry more weight than broad descriptions.
Prepare for Pushback
Insurers often test whether the evidence is consistent across records. Adjusters compare the crash account with medical histories, social media, employment records, and recorded statements. A case team reviews those materials early, corrects genuine errors, and explains harmless differences before they become negotiation points.
Settlement discussions also require attention to deadlines and release language. A signed release can end claims that were not fully evaluated, while an unresolved lien can reduce the money received. Legal review should occur before a claimant accepts payment, gives a recorded statement, or signs any insurer document.
Protecting the Claim Before the Insurer Responds
An insurer’s first response does not determine the outcome of a collision claim. The evidence assembled before that response shapes the discussion, especially when liability, treatment, or income becomes disputed. A claimant should preserve records, follow medical instructions, avoid casual statements, and seek legal review before signing a release. That early review can expose missing proof and protect deadlines. A case built around verified facts gives negotiations a clear foundation and gives the claimant a reasoned basis for the next decision.
